Portfolio Update: October Allocations, Fortinet Reaction & FCF Yield Trends
Three updates this week.
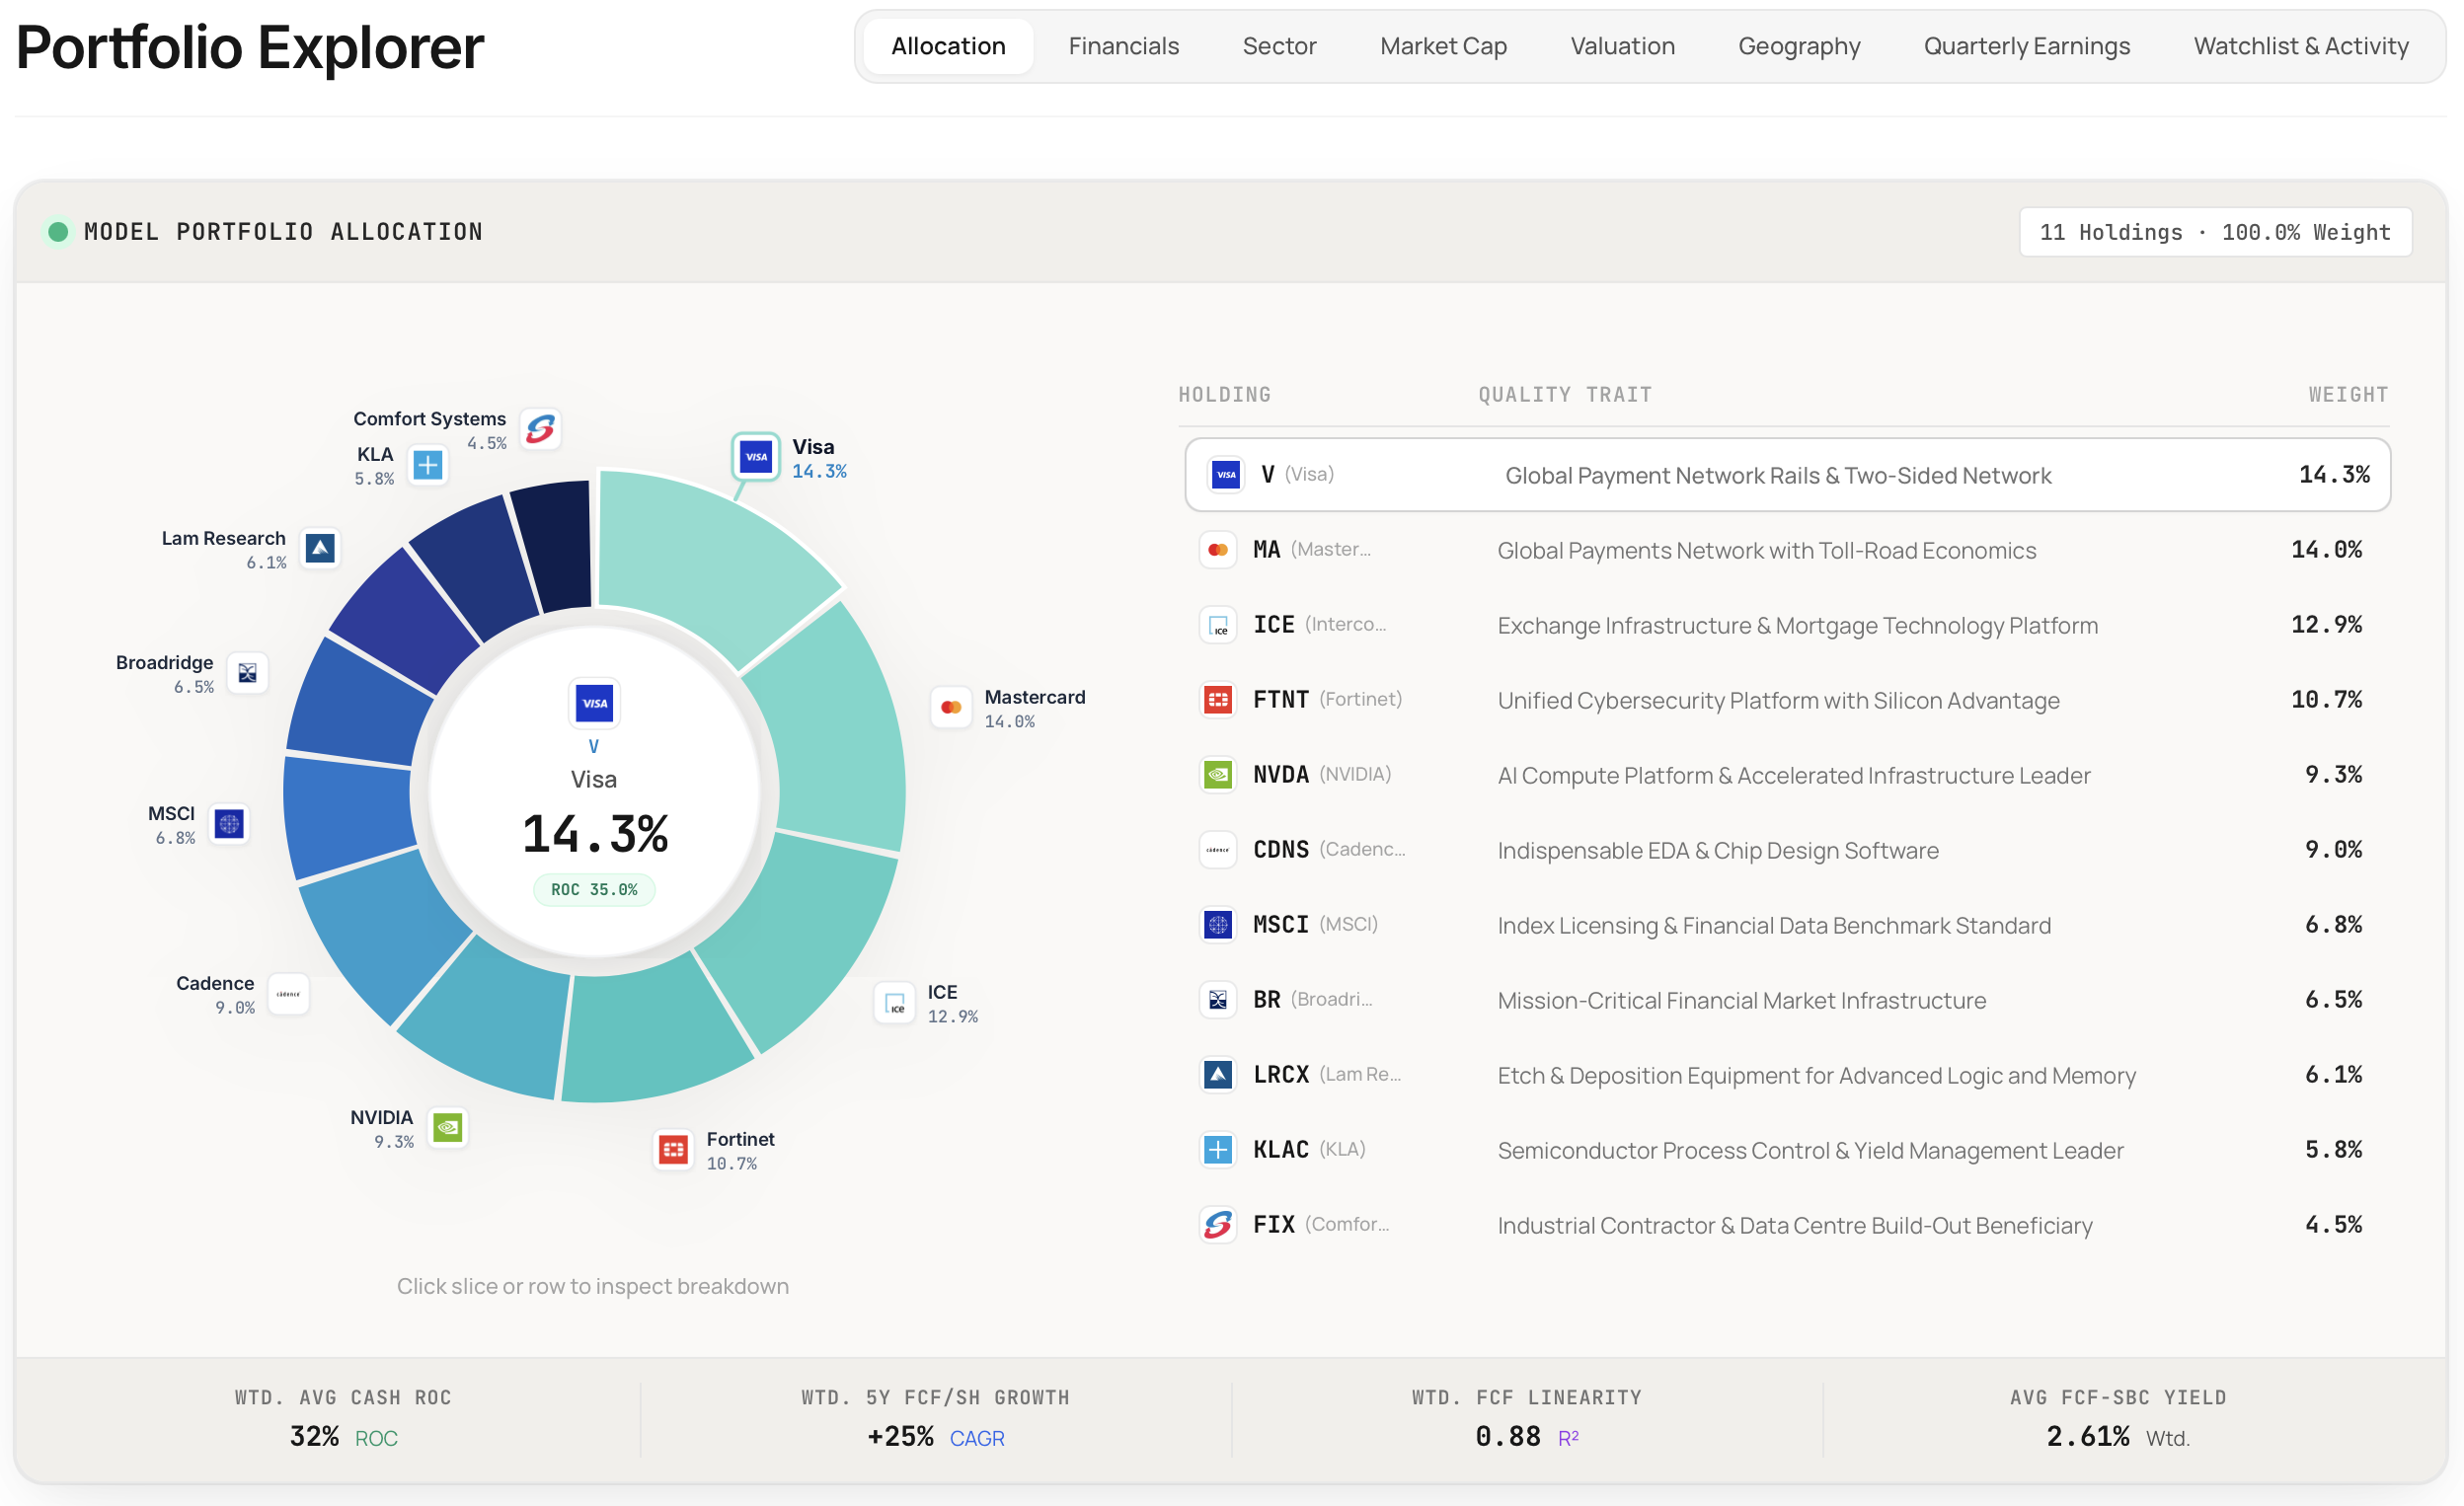
First, I've updated the Portfolio page following the end of October. The current allocations can be seen below.
Second, we're almost done with this quarter's earnings releases, which are summarised below. We're still waiting for Broadridge (which is tomorrow) and NVIDIA (which is 18 Nov).
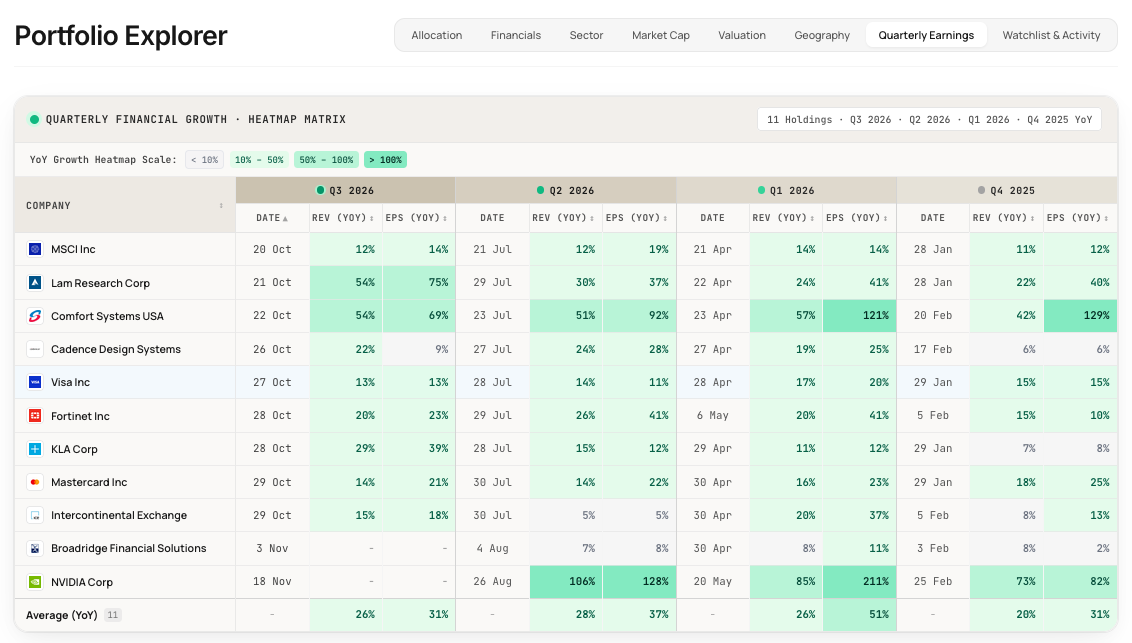
It's worth pointing out that despite Fortinet reporting 20% revenue growth and 23% EPS growth, the market responded with a 30% drop. This was primarily due to a slowdown in high-margin service revenue and fears that hardware demand was pulled forward. While this is a mostly rational response to some deceleration in subscription growth, the severity of the sell-off possibly overlooks the strong deferred billings that point to revenue recognition lags rather than customer churn. For this reason, I will continue to hold Fortinet.
Lastly, I'm currently working on a comparative valuation tool. Here's a sneak peak. The below chart shows the FCF yield over the last 10 years for a selection of large cap quality companies.
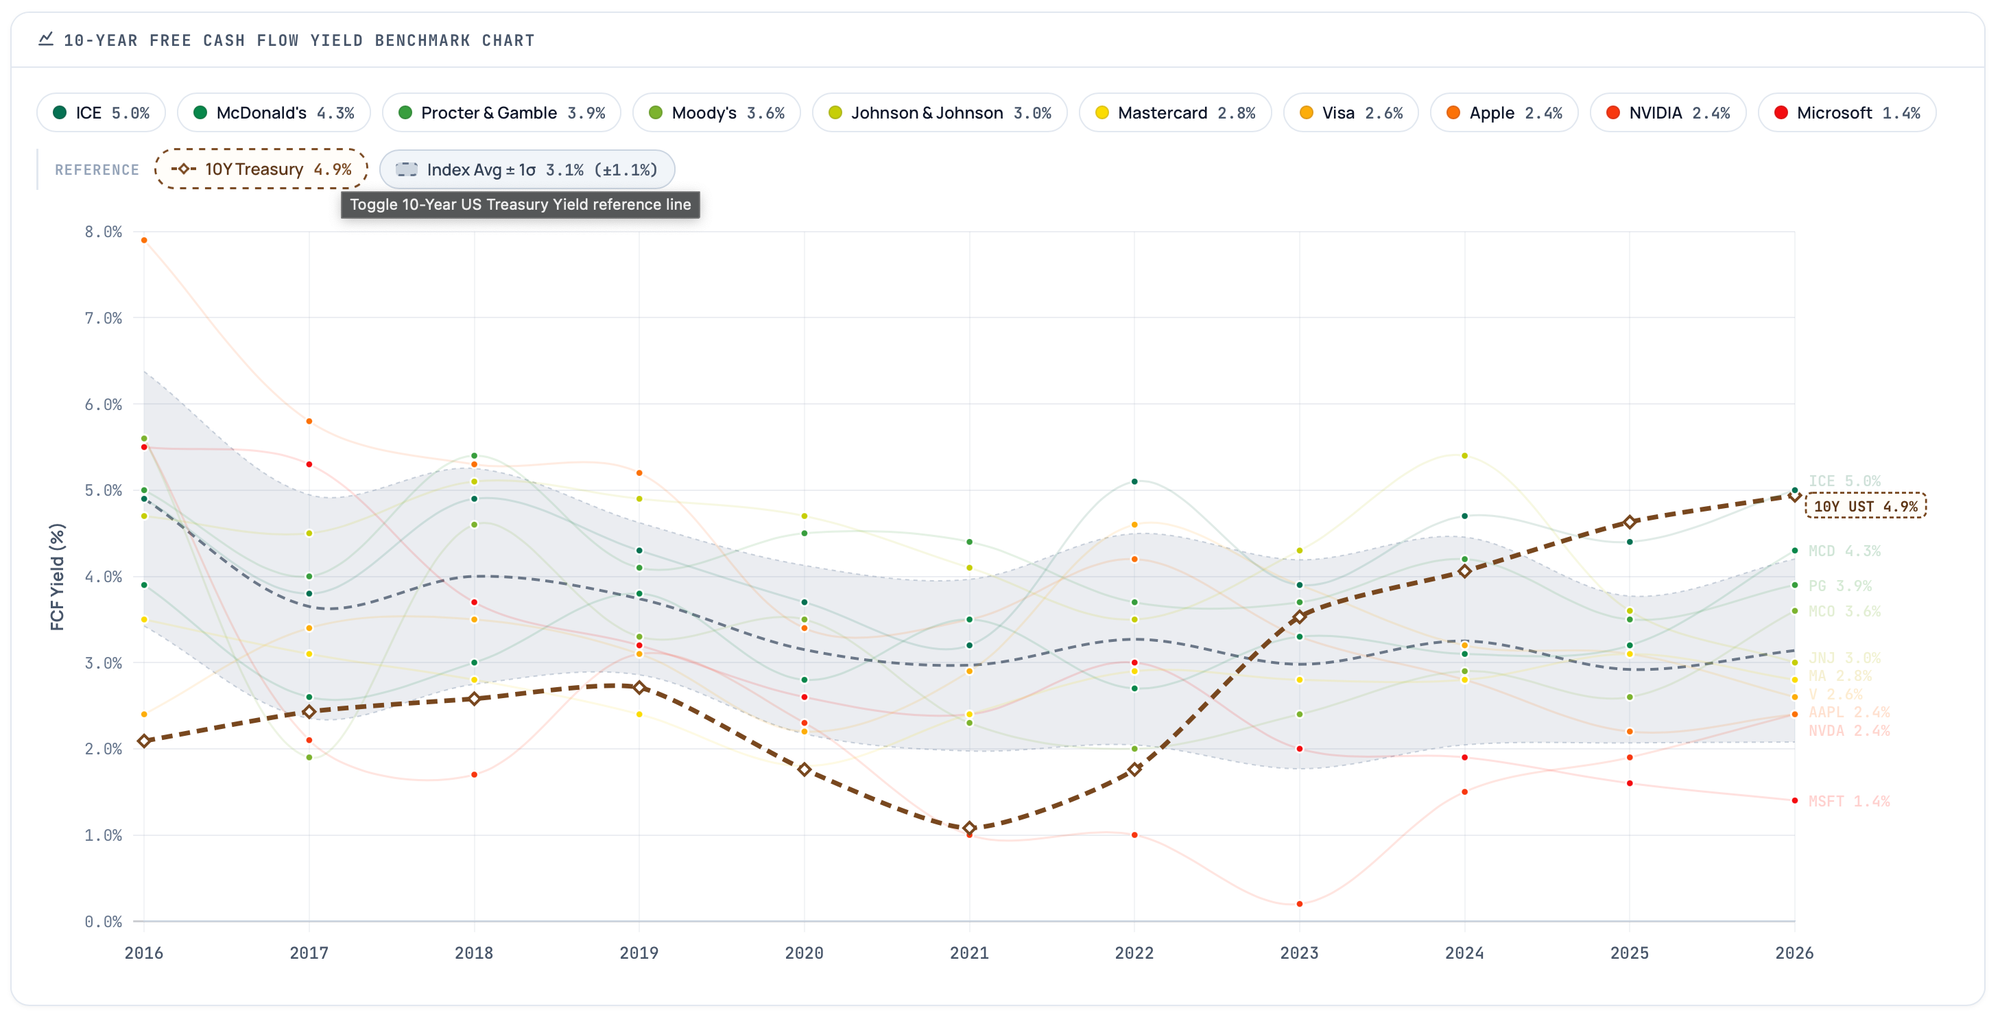
Something worth noting from the chart is that in 2022 the 10Y US Treasury yield surpassed the average quality companies' FCF yield. This is the result of rapid rate hikes from the Fed and heavy government debt issuance forcing Treasury yields up to compensate for inflation. Meanwhile, quality companies have seen their FCF yields stay low, because investors has bid up their share prices on the expectation of future growth. This means that low risk assets have higher returns than riskier assets (i.e. equities). Something to keep watch of.
Until next time.
Long Equity